
What founders on Equidam planned to raise in H1 2026, how that compares with data on closed rounds, and a simple way to size your own round from runway, milestones and dilution.
In H1 2026, pre-seed founders on Equidam planned to raise a median of $0.52M worldwide. The US median was $1.90M and the European median $0.71M, at median pre-money valuations of $5.16M and $3.30M (Startup Valuation Delta H1 2026). These are planned raises, not closed rounds. Aim for 18 to 24 months of runway to your next milestone.
Data as of: Equidam Startup Valuation Delta H1 2026, published July 2026. External figures are dated where they appear. Page updated October 2026.
The regional figures show what other founders at your stage plan to raise. The right amount for your company comes from your own burn rate and your next milestone, so this guide covers the benchmarks first, then a three-step method to size your round and check the dilution.
Pre-seed round sizes in 2026: what founders plan to raise, by region
We publish the Startup Valuation Delta, a report built from pre-seed valuations founders complete on Equidam. The H1 2026 edition covers valuations completed between January and June 2026. Two of the fields in each valuation are the pre-money valuation and the “capital requirement”, which is the amount the founder says they plan to raise. We define pre-seed as a company with nothing beyond a minimum viable product (MVP) that is raising its first institutional round, with no venture capital firm on the cap table.
| Region | Median planned raise (USD M) | Median pre-money valuation (USD M) | Implied dilution (%) |
|---|---|---|---|
| United States | 1.90 | 5.16 | 26.9 |
| Oceania | 1.00 | 3.26 | 23.5 |
| Europe | 0.71 | 3.30 | 17.7 |
| Middle East | 0.63 | 5.56 | 10.3 |
| South East Asia | 0.57 | 3.84 | 12.9 |
| Latin America | 0.45 | 2.40 | 15.8 |
| Africa | 0.39 | 2.99 | 11.6 |
| Global (all H1 2026 valuations) | 0.52 | 5.20 | 9.7 (Q1), 8.5 (Q2) |
Source: Startup Valuation Delta H1 2026, Equidam platform data, H1 2026. The global row covers all H1 2026 valuations and is published separately, so it is not an average of the regional rows above. Global implied dilution is published by quarter. Each H1 2026 figure is the average of the Q1 and Q2 2026 medians, weighted by the number of valuations in each quarter, which is why the edition’s regional table labels its columns “Avg.”.
Read the table with three caveats in mind.
First, these are plans, not closed deals. The figures show what founders intended to raise while they prepared for a round. Some will raise more, many will raise less, and some will not close at all. Our analysis of funding odds covers that side of the story.
Second, implied dilution is a ratio of medians. It is the median planned raise divided by the median post-money valuation (pre-money plus the raise). In the edition’s own words, it is “what a founder would give up if they raised the median capital requirement at the median valuation”. It is not the median of individual deals. That is why the US figure of 26.9% looks high: American founders on Equidam plan to raise 2.7 times as much as European founders, at a valuation that is only about 56% higher.
Third, smaller regions move on thin data. The H1 2026 edition reads Oceania and South East Asia as directional only. Treat a single-region figure as a starting point, then build your own number.
Use all of these figures as a sanity check on a number you have built yourself, not as a target. A median describes the middle of the distribution, and investors at pre-seed are looking for companies that will not end up in the middle.
What closed-round data says
External sources measure something different: rounds that actually closed. They also define “pre-seed” and “seed” differently, so line them up with care.
| Source | Geography | What it measures | Figure | Period |
|---|---|---|---|---|
| PitchBook-NVCA Venture Monitor | US | Median seed deal value, closed VC deals | $3.0M (down from $3.4M in 2025) | 2026 to 30 Sep |
| Carta | Startups on Carta | Median seed round and dilution | $4.5M raised at a $23.9M post-money, 19.4% dilution | Q2 2026 |
| Carta State of Pre-Seed | US, startups on Carta | Average size of one pre-seed SAFE or convertible note | $276,000 | Q2 2026 |
| Dealroom | Europe | Total capital raised before Series A | About $2.5M to $3M | Dealroom startup-journey benchmark (undated) |
What US pre-seed founders on Equidam planned to raise ($1.90M) sits between a single SAFE on Carta ($276,000 on average; a round can combine several, and Carta reports that deals above $2.5M typically stack ten or more) and a full closed seed round ($3.0M median on PitchBook). That is roughly where you would expect a first institutional round to land. For Europe we found no 2026 primary source with a median closed pre-seed round size, so our planned-raise figure of $0.71M is the closest current European reference, with the caveat that it measures intentions.
If you are raising in the UK, our earlier page on how much UK startups raise adds UK context, based on 2020-2021 data.
How planned pre-seed raises have changed since 2019
| Year | Median pre-money valuation (USD M) | Median planned raise (USD M) |
|---|---|---|
| 2019 | 2.49 | 0.32 |
| 2020 | 4.55 | 0.67 |
| 2021 | 5.10 | 0.66 |
| 2022 | 7.20 | 0.75 |
| 2023 | 5.71 | 0.63 |
| 2024 | 4.76 | 0.47 |
| 2025 | 5.28 | 0.65 |
| H1 2026 | 5.20 | 0.52 |
Source: Startup Valuation Delta H1 2026, global medians, all regions. Each figure is the average of that period’s quarterly medians, weighted by the number of valuations in each quarter.
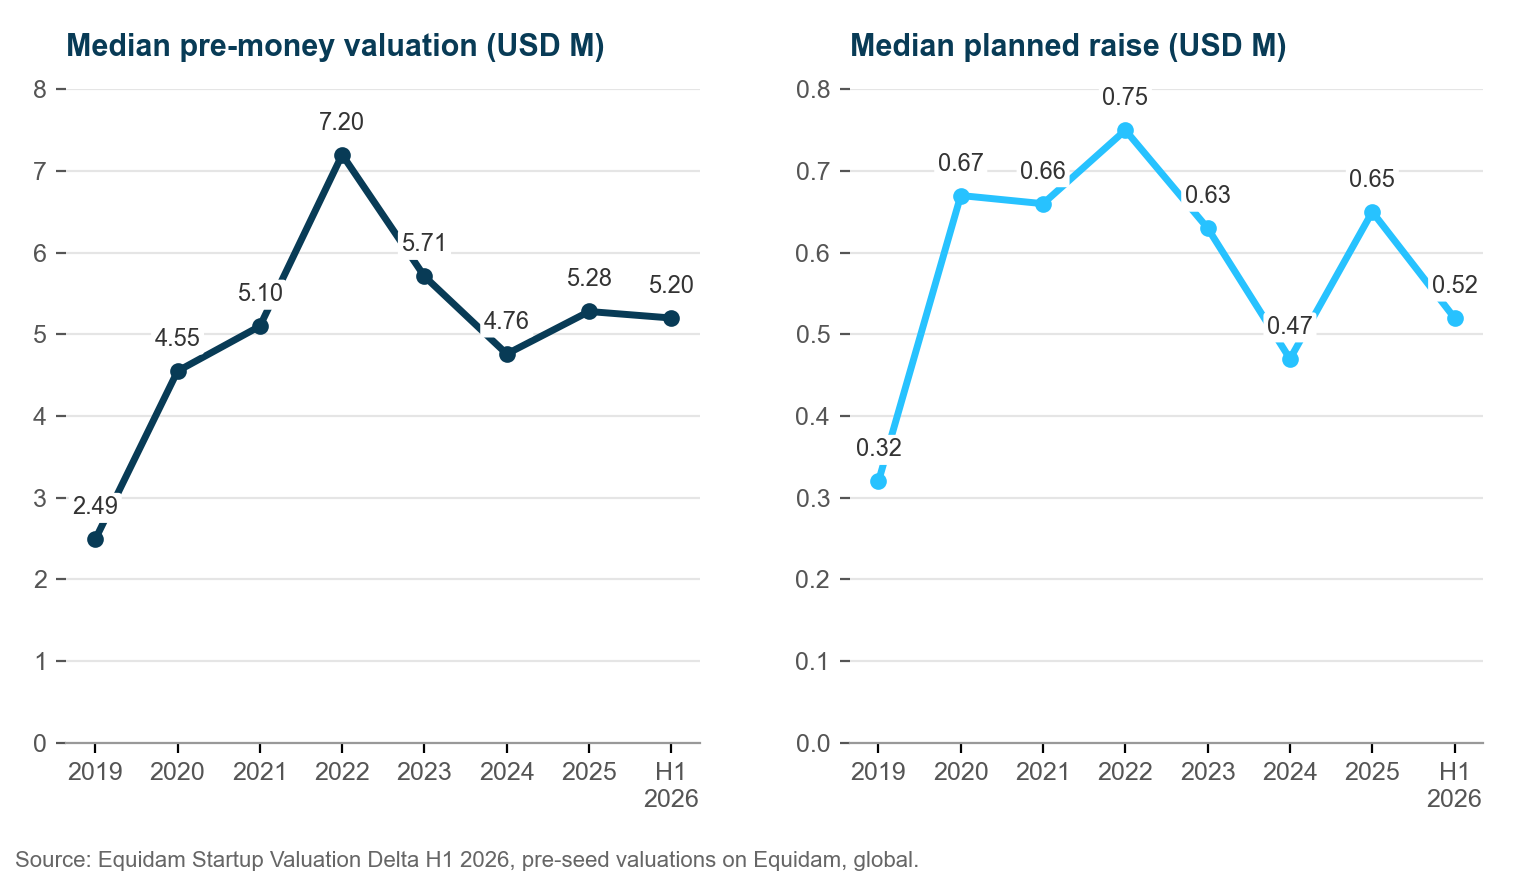
The median planned raise peaked at $0.75M in 2022, fell to $0.47M in 2024, rebounded to $0.65M in 2025 and came back to $0.52M in H1 2026. The median valuation fell from $7.20M in 2022 to $4.76M in 2024 and has held near $5.20M since. The quarterly implied dilution came in at 9.7% in Q1 2026 and 8.5% in Q2 2026, at the low end of a band that has run from roughly 7% to 21% since 2019 (Startup Valuation Delta H1 2026). In plain terms, founders are planning smaller rounds than in 2025, and the share of the company they expect to sell sits near the bottom of its range since 2019.
Three ways to size your round
A regional median cannot tell you how much your company needs. Use three checks, in this order, and stop when they agree.
1. Runway: how long the money has to last
Runway is the number of months your cash covers at your current net burn (cash out minus cash in each month). Our guide to burn rate explains how to measure it on a cash basis rather than an accounting basis, which matters because invoices do not pay salaries.
Runway formula
Amount to raise = monthly net burn × (months to your next milestone + months needed to raise the next round)
We have long used a simple rule of thumb: plan 12 months of runway, then add a 50% cushion, for 18 months in total. The extra six months cover delays in your plan and the time it takes to raise again. Most guidance today lands in the same place. Carta, for example, notes that most founders aim to fund 18 to 24 months of operations with a seed round. Dealroom finds that European companies took a median of about 24 months to get from seed to Series A, and notes the actual gap is likely longer once reporting lags are included, so in Europe the top of that range is the safer planning figure.
2. Milestones: what must be true to raise again
Your next round will be priced on what you have proven by then. Before you pick a number, write down the two or three things that must be true when you start raising again. These might be a set level of recurring revenue, a product in the hands of paying customers, a regulatory approval or a working prototype at production cost.
Then cost them. Hiring plans, development time, sales cycles and marketing spend all go into the budget that gets you there. We sometimes call this approach “island hopping”: you raise enough to reach the next island, where a milestone you have proven lets you raise on better terms. If the milestone budget is larger than your runway figure, the runway figure is too small. If it is much smaller, you may be raising money you do not yet need, at today’s lower valuation.
Industry changes the answer. Software is usually cheap to start and gets more expensive as it scales. Hardware, life sciences and games often need much more capital before the first revenue arrives. Those founders have to raise more while the risk is still high, so each euro raised tends to cost them more equity.
3. The dilution check: what the round costs you in ownership
Once you have a number, test it against your valuation.
Dilution formula
Dilution = amount raised ÷ post-money valuation, where post-money = pre-money + amount raised
Our guide on how much equity to give away per round explains why many operators aim for roughly 15% to 25% per round, with pre-seed at the lower end. Carta reports median seed dilution of 19.4% in Q2 2026. If your round lands well above that range, you have three levers: raise less, spend less, or support a higher valuation with stronger evidence. For more worked examples of the formula, see Dilution 101.
Most pre-seed money now comes through SAFEs: among US startups on Carta, 93% of pre-seed rounds in Q2 2026 used them. With a post-money SAFE, the valuation cap plays the role of the post-money valuation, so each investor’s stake is roughly their investment divided by the cap. Several SAFEs at different caps add up when they convert, so model them together rather than one at a time.
Worked example: a European B2B SaaS startup
Take a European B2B software company with four people and early pilot customers. All figures here are hypothetical.
- Net burn: €45,000 a month.
- Next milestone: enough recurring revenue to raise a seed round, which the founders expect to reach in 14 months.
- Time to raise the next round: six months.
- Runway needed: 14 + 6 = 20 months.
- Amount to raise: €45,000 × 20 = €900,000.
- Pre-money valuation: €3.5M, a round number chosen for the example.
- Post-money valuation: €3.5M + €0.9M = €4.4M.
- Dilution: €0.9M ÷ €4.4M = 20.5%.
At 20.5%, the founders are inside the 15% to 25% range, though toward the top of what is usual at pre-seed. If they want to give up less, they have three realistic options:
- Raise less equity and add non-dilutive money. Raising €700,000 in equity at the same €3.5M pre-money costs 16.7% (€0.7M ÷ €4.2M). A €200,000 grant or innovation loan covers the remaining runway.
- Spend less. Cutting net burn to €38,000 a month brings the 20-month need to €760,000, which is 17.8% dilution at a €3.5M pre-money.
- Support a higher valuation. To raise the full €900,000 for 18% dilution, the pre-money would need to be about €4.1M. That only works if the founders can show evidence, such as revenue, retention or a strong team, that supports the higher number.
What they should not do is raise €500,000 to keep dilution low. At €45,000 a month that buys about 11 months, three months short of the milestone, and the next round would start from a weak position.
Raising too much vs too little
Raising too much at pre-seed usually means selling more of the company at its lowest valuation. It can also set a valuation the company then struggles to grow into, which raises the risk of a down round later. Large early rounds create pressure to hire and spend before the core assumptions are proven, a pattern often described as premature scaling.
Raising too little means the company runs out of cash before the milestone, the next raise starts from a weak position, and the founders either accept worse terms or spend months fundraising when they should be building.
When to raise
The best time to raise is after a milestone, not before it. A valuation rises as you prove your assumptions, so a round that starts with fresh evidence, such as first revenue or a signed pilot, will usually be priced better than one that promises the same evidence later.
Timing in the calendar matters too. In our experience there are two main fundraising windows: a long one from January to July and a shorter one from September to December. If you start in October, be confident you can close before the holidays. Otherwise it is often better to prepare properly and start in January.
Start raising the next round while you still have about six months of cash left. A round takes months from first meeting to money in the bank, and a company with three months of runway negotiates from a weak position.
Set your valuation before you set your ask
The amount you raise and your valuation are two halves of the same decision. You cannot judge whether €900,000 is a sensible ask until you know what the company might be worth, because the valuation decides how much of the company that money costs.
A valuation is an estimate built on assumptions, so the best way to prepare for that conversation is to make the assumptions visible. Equidam combines five valuation methods: the Scorecard and Checklist methods, the VC method, and two discounted cash flow (DCF) methods, one with long-term growth and one with exit multiples. The weight of each method changes with the company’s stage, and the DCF methods adjust for survival rates and an illiquidity discount. The result is a defensible range that you can explain to an investor, rather than a single number you have to argue for. To compare with announced rounds in your own market, our page on average startup valuation by country lists pre-seed and seed valuations for 88 countries and territories. You can see the plans and run a valuation here.
FAQ
How much do startups raise at pre-seed?
In H1 2026, pre-seed founders on Equidam planned to raise a median of $0.52M worldwide, against $1.90M in the US and $0.71M in Europe (Startup Valuation Delta H1 2026). These are planned amounts, not closed rounds. On Carta, the average US pre-seed SAFE or note was $276,000 in Q2 2026, and one round can combine several.
How much should I raise in a seed round?
Raise enough to reach the milestone your Series A investors will want to see, plus time to raise. For reference, the median US seed deal was $3.0M in 2026 to 30 September, according to PitchBook-NVCA. Size yours from your burn and milestones first, then compare it with the benchmarks.
How many months of runway should a round give?
Plan for 18 to 24 months. Our rule of thumb is 12 months plus a 50% cushion, so 18 months. In Europe, where Dealroom finds a median of about 24 months between seed and Series A, aim for the top of the range.
How much equity should I give away at pre-seed?
Many founders aim for the lower end of the common 15% to 25% per-round range. Based on what they planned to raise, implied dilution for pre-seed founders on Equidam was 17.7% in Europe and 26.9% in the US in H1 2026. Our guide on how much equity to give away covers the long-term effects.
Do European startups raise less than US startups?
Yes, at pre-seed. In H1 2026, European founders on Equidam planned to raise a median $0.71M, against $1.90M in the US, at median pre-money valuations of $3.30M and $5.16M (Startup Valuation Delta H1 2026). Their implied dilution, based on planned raises, was also lower: 17.7% against 26.9%.